All Categories
Featured
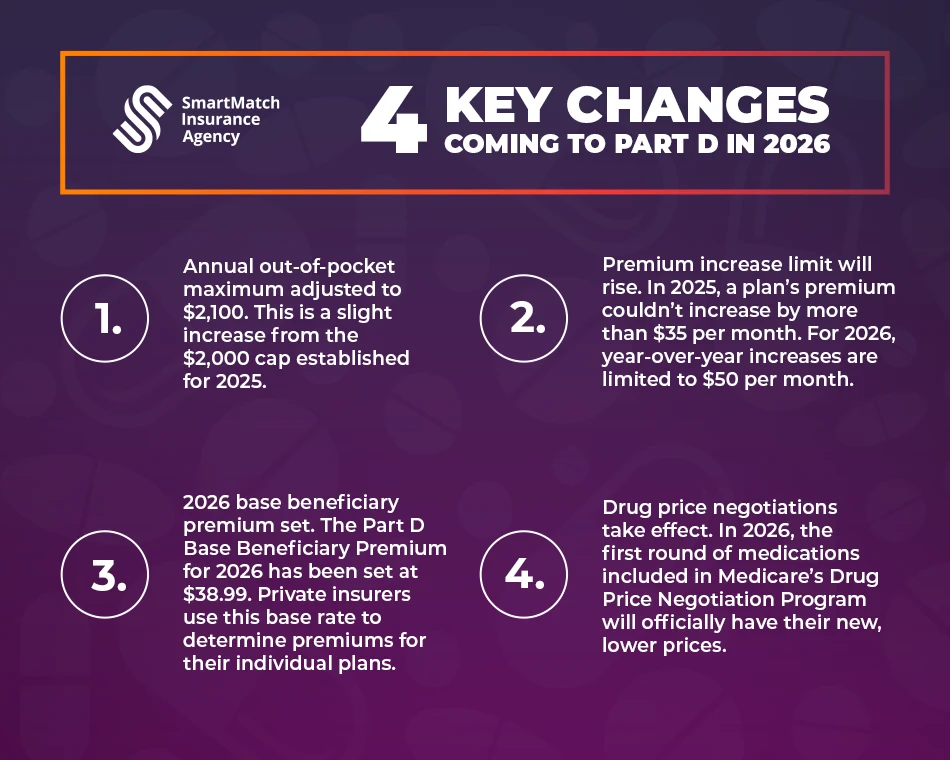

Comparing Cheap Medicare Coverage for 2026
Table of Contents
Like all health insurance, getting in-network care is best to keep your out-of-pocket expenses low. Unlike HMO plans that won't cover any portion of your expense if you seek out-of-network care (except in a covered emergency), you can get out-of-network care when taking a trip out of your regular strategy network location with a PPO policy.
Insurance in San Juan Capistrano CACost-conscious individuals need to think about a few downsides to PPO prepares that may make getting care more pricey. While they're flexible and practical, PPO plans have greater premiums.

If you do have a deductible, it's likely to be more costly than other plan types. While your insurance provider will share the expense with you, you'll likely pay a higher coinsurance portion for out-of-network providers. When you check out an in-network service provider, they'll file your claim to your health insurance company on your behalf.
PPO policyholders might discover the claim filing process made complex if they're not used to it or time-consuming if they frequently need out-of-network care from a specialist. In 2023, the average yearly premium for a group PPO strategy was $8,906 for self-only coverage and $25,228 for household coverage2. Companies contributed $7,399 towards a self-only plan, and workers contributed $1,507.
Low-Cost Plan Choices for Veterans
The average deductible for PPO plans was $1,281. As mentioned above, PPO plans acquired on the ACA marketplaces also have an optimum out-of-pocket limitation of $9,450 for self-only coverage and $18,900 for family plans. To summarize how HMO and PPO strategies differ, examine out our fast chart. Self-only coverage: $8,203 Family protection: $23,758 Self-only coverage: $8,906 Household coverage: $25,228 For 2024 ACA market plans, the maximum limit is $9,450 for self-only protection and $18,900 for family protection.
Yes No Yes No Some plans do. A lot of strategies do. Yes. But if they do, they are accountable for paying the entire bill on their own unless the care was for an emergency. Yes. Individuals may have a higher coinsurance or medical expense. Whether you have an HMO or PPO strategy, you can utilize a health compensation plan (HRA) to lower out-of-pocket medical costs.
Insurance in San Juan Capistrano CAJust employers can introduce and contribute toward an HRA. Companies utilize an HRA to provide their employees a monthly allowance to pay for medical expenses. As soon as an employee buys an eligible item or service, they send documentation showing evidence of purchase, and their employer reimburses them approximately their allowance amount.
Optimizing Indexed Universal Life Growth Benefits in Retirement
(MEC). (ICHRA): An ICHRA is also a stand-alone HRA, but it's available to companies of all sizes and has no contribution limitations.

They need to have a qualifying form of individual health coverage to take part. (GCHRA): Likewise known as an incorporated HRA, a GCHRA is for companies of any size who offer a group health plan. Only workers enrolled in their company's group plan can take part.
While they have no optimum contribution limits, the IRS doesn't allow compensations for month-to-month premiums. No matter whether it's utilized in coordination with an HMO or PPO strategy, there's an HRA that can assist workers pay for their out-of-pocket medical expenses and, in some cases, their health insurance premiums. An HRA is a popular alternative option over conventional health advantages since they're economical for companies and versatile enough for each staff member.
Comparing PPO vs HMO Insurance
An HMO might be your finest bet if you're looking for a strategy with a low premium. A PPO strategy provides additional versatility if you need more control over your health care. That's why researching these plans thoroughly, including their pros, cons, and typical expenses, is the finest primary step you can take in the past making a decision.
(MEC). (ICHRA): An ICHRA is likewise a stand-alone HRA, but it's offered to employers of all sizes and has no contribution limits.
They need to have a qualifying kind of private health protection to participate. (GCHRA): Also known as an incorporated HRA, a GCHRA is for companies of any size who provide a group health strategy. Just employees registered in their employer's group plan can get involved.
2026 Whole Life Insurance Prices for American Families
While they have no optimum contribution limitations, the internal revenue service doesn't allow repayments for monthly premiums. No matter whether it's utilized in coordination with an HMO or PPO strategy, there's an HRA that can help employees pay for their out-of-pocket medical costs and, in some cases, their health insurance premiums. An HRA is a popular alternative choice over conventional health advantages due to the fact that they're budget-friendly for companies and flexible enough for each employee.
An HMO may be your best choice if you're trying to find a plan with a low premium. A PPO plan offers extra versatility if you need more control over your health care. That's why investigating these strategies thoroughly, including their pros, cons, and average expenses, is the finest first step you can take before deciding.

Latest Posts
Comparing Cheap Medicare Coverage for 2026

Selecting the 2026 Medicare Advantage Coverage
Choosing HMO vs PPO Health Insurance Plans